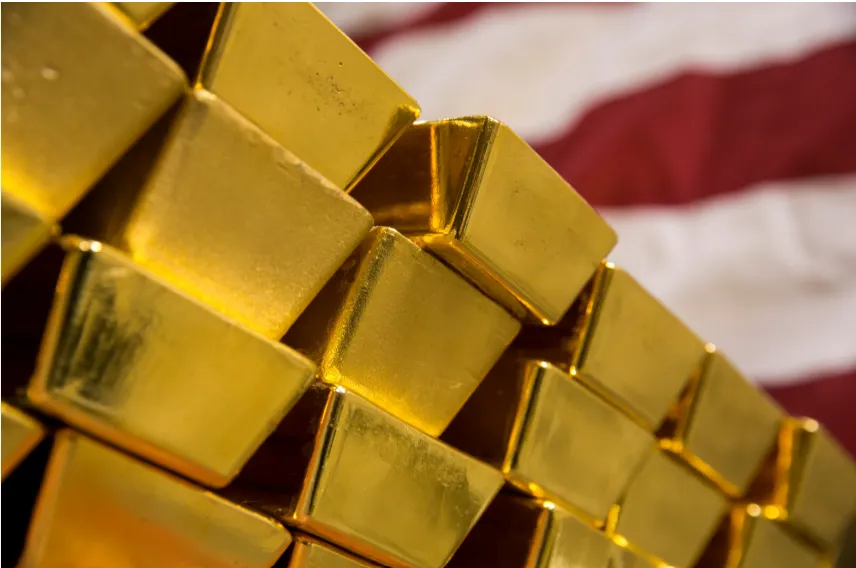
European central banks are increasingly reviewing the location of their gold reserves, with the Netherlands becoming the latest country to shift a significant portion of its holdings from North America to London.
The Dutch central bank, De Nederlandsche Bank (DNB), confirmed this week that it had relocated 86 tonnes of gold previously held in the United States and Canada. The move, carried out between March and August, was described as part of efforts to strengthen the Netherlands' preparedness for potential severe crises amid growing geopolitical uncertainty.
The transferred gold is now stored in the vaults of the Bank of England in London, one of the world's major centres for gold trading and custody.
Netherlands shifts 86 tonnes to London
The Netherlands held about 313 tonnes of gold in the United States and Canada before the latest relocation. DNB said moving 86 tonnes to London would make the reserves more readily accessible if they were needed during a crisis.
"We expect that we will never need to use them, but we do need to strengthen our resilience and preparedness," DNB Governor Olaf Sleijpen said.
The decision does not appear to indicate that Dutch authorities are expecting an imminent economic collapse or other major crisis. Instead, analysts and industry representatives point to a broader reassessment by central banks of how their reserve assets should be managed.
Why London?
London has long been a major international centre for gold trading, making it an attractive location for central banks that want their reserves to be quickly accessible.
The Bank of England is among the world's largest gold custodians. Its vaults beneath the historic central London institution contain roughly 400,000 gold bars, with a reported value exceeding £200 billion.
Industry surveys by the World Gold Council continue to identify the Bank of England as the most popular location for gold storage, although central banks are increasingly considering diversification between different locations.
Goldman Sachs analysts Lina Thomas and Daan Struyven said the location of gold reserves has become increasingly important for reserve managers.
The gold does not always have to cross borders
Moving gold between countries does not necessarily mean physically transporting every bar.
In the Dutch case, around 59 tonnes were sold in New York and replaced with gold purchased in London. That approach allowed the Netherlands to change the location of its holdings without transporting the same physical bars across the Atlantic.
More than 27 tonnes, however, were physically moved from the United States and Canada to the Netherlands. A similar quantity was subsequently transferred from the Netherlands to London.
International gold transportation involves specialized companies and extensive security arrangements. Brink's Global Services, which provides such services, said it has experienced increased demand from central banks.
Brink's executive vice president Nader Antar attributed the trend to greater geopolitical and economic uncertainty, together with gold's expanding importance as a strategic reserve asset.
European countries have been reassessing gold storage for years
The Netherlands is not alone in reviewing the location of its reserves.
France announced earlier this year that it had brought its gold holdings from the United States back to France. Germany's Bundesbank also completed a major repatriation programme in 2016, transferring more than 216 tonnes from overseas storage locations — 111 tonnes from New York and 105 tonnes from Paris.
The practice also has historical precedent. Goldman Sachs analysts noted that some European central banks moved portions of their gold holdings to New York during the Cold War, when geopolitical considerations influenced reserve management.
Geopolitical tensions are only part of the picture
Although wars, trade disputes and geopolitical tensions are influencing decisions about reserve storage, the World Gold Council says they are not necessarily the main reason behind the latest moves.
Joseph Cavatoni, a senior market strategist at the World Gold Council, told the BBC that geopolitical tensions were contributing to decisions but were not "top of the list" of motivations.
Other factors include inflation, interest rates, liquidity and the ability to trade gold quickly.
Cavatoni said central banks are becoming more sophisticated in how they manage reserve assets and are paying greater attention to how those holdings can be used during periods of uncertainty.
Central banks are buying more gold
The discussion about gold storage comes as central banks have significantly increased their purchases of the precious metal.
According to the World Gold Council, central banks have accumulated an average of around 1,000 tonnes of gold annually over the past four years, compared with roughly 500 tonnes a year during the preceding decade.
The trend has strengthened since the global financial crisis and is expected to continue into the next year.
Gold has also experienced a substantial rise in value. Its price surpassed $5,000 per troy ounce in January 2026, later reaching an inflation-adjusted peak of about $5,394 in February, according to the data cited in the report.
By July 2026, gold stood at approximately $4,046 per ounce, remaining significantly above many historical levels despite falling from its early-2026 peak.
Goldman Sachs researchers cited in the report forecast that gold could reach $4,900 per troy ounce by the end of 2026, around $300 above its August level.
What the moves mean
The relocation of gold should not automatically be interpreted as evidence that European governments expect a major financial crisis.
Instead, the moves illustrate how central banks are reconsidering the management of their reserve assets in an environment characterized by geopolitical tensions, changing interest rates, inflation concerns and increased demand for gold.
Storing gold domestically can provide greater direct control, but it also requires substantial investment in physical security, auditing systems and insurance. Goldman Sachs analysts noted that these costs can be particularly significant for smaller central banks.
For the Netherlands, London offers a compromise: its gold can remain outside North America while being located close to one of the world's most active gold markets.
As central banks continue accumulating gold, the question of where those reserves should be stored and how quickly they can be accessed is likely to remain an important part of reserve management.